
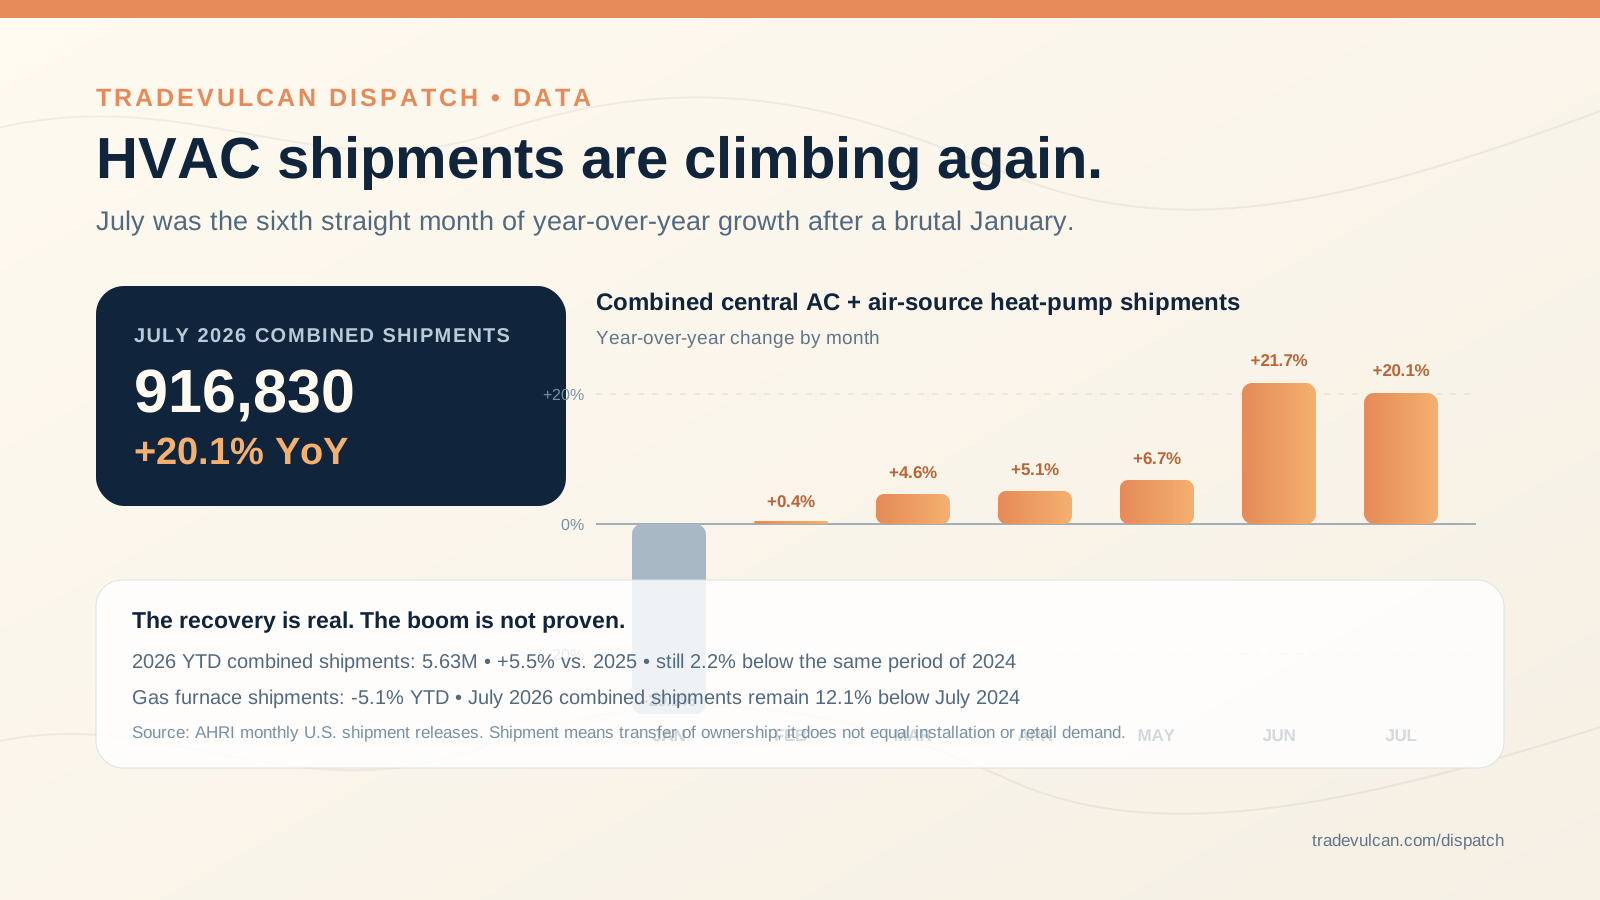
The fresh number: 916,830 units
The Air-Conditioning, Heating, and Refrigeration Institute released its July 2026 U.S. shipment data on September 11. Combined shipments of central air conditioners and air-source heat pumps reached 916,830 units, up 20.1% from July 2025. Central-air shipments increased 22.3% to 503,151 units, while air-source heat pumps increased 17.6% to 413,679.
This is shipment data, not installation data. AHRI defines a shipment as a transfer of ownership and says the figures cover customers in the 50 states and District of Columbia, whether the equipment was produced domestically or imported. The association explicitly says it does not forecast or interpret market trends. The analysis below is TradeVulcan Dispatch's interpretation of the published series.
The HVAC equipment channel has clearly improved. That is not the same thing as declaring a boom.
January looked ugly. Combined central-air and heat-pump shipments fell 29.2% from a year earlier to 440,819 units.
Then the direction changed. February turned slightly positive. March, April and May added progressively stronger gains. June jumped 21.7%. July followed with another 20.1% increase. Industry publication HomePros, reviewing the AHRI series, identified July as the sixth consecutive month of year-over-year growth after nine straight months of declines beginning in May 2025.
That is a real recovery signal. It is also a recovery from a weak comparison base. July 2025 itself was almost 27% below July 2024. Even after this July's 20.1% rebound, combined volume remained about 12.1% below July 2024.
The year-to-date comparison tells the same story. Through July, combined 2026 shipments are up 5.5% from 2025, but at 5.63 million units they remain about 2.2% below the 5.76 million units shipped over the same period in 2024.
For contractors, the useful conclusion is neither “demand is collapsing” nor “the boom is back.” The equipment channel has moved from contraction into recovery. The next question is whether that improvement is showing up as more qualified replacement opportunities, stronger close rates and healthier installed gross profit in local markets.
What HVAC operators should take from the release
- Combined central AC and air-source heat-pump shipments rose 20.1% year over year in July to 916,830 units, according to AHRI.
- July marked a sixth straight month of year-over-year combined shipment growth after January's 29.2% decline and a nine-month contraction streak that began in May 2025, according to HomePros' review of the AHRI series.
- The comparison base matters: July 2026 combined shipments were still about 12.1% below July 2024's 1,043,420 units.
- Through July, combined shipments are up 5.5% versus 2025 but remain about 2.2% below the same seven-month period in 2024.
- Heat pumps continue taking a larger share of the combined AC/heat-pump mix: 45.6% of 2026 year-to-date combined shipments versus 42.1% over the same period in 2024.
- Gas warm-air furnaces are moving differently. July shipments rose 2.1%, but year-to-date volume remains down 5.1% from 2025.
- Shipment growth is not proof of contractor demand. Owners should reconcile the national equipment data against local leads, replacement opportunities, close rates, average tickets, financing usage, cancellations and distributor inventory.
July 2026 HVAC shipment scorecard
- AC + heat pumps
- 916,830
- Central AC
- 503,151
- Air-source heat pumps
- 413,679
- 2026 YTD combined
- 5.63M
- Gas furnaces YTD
- -5.1%
- Growth streak
- 6 months
+20.1% versus July 2025.
+22.3% versus July 2025.
+17.6% versus July 2025.
+5.5% versus 2025, but about 2.2% below 2024.
1,818,744 units through July.
February through July posted positive year-over-year combined shipment growth.
The recovery looks much stronger when you start the chart in January
The most useful part of the July release is not the 20.1% headline by itself. It is the shape of 2026.
January's 440,819 combined units represented a 29.2% year-over-year decline. February edged into positive territory at 0.4%. March improved to 4.6%, April to 5.1%, May to 6.7%, June accelerated to 21.7%, and July held near that pace at 20.1%.
That sequence suggests the channel has moved through more than a one-month weather spike. Six consecutive positive comparisons are harder to dismiss than a single strong print.
But the sequence also begins from a very depressed starting point. Calendar-year 2025 combined AC and heat-pump shipments fell 20% from 2024, according to AHRI's December 2025 release. The market entered 2026 with a deep hole to climb out of. A strong percentage increase against a weak prior-year month can coexist with absolute volume that remains below the earlier cycle peak.
That is exactly what July shows. The 916,830 units shipped this July are well above 2025's 763,443—but still below the 1,043,420 units shipped in July 2024.
2026 combined central AC + heat-pump shipment trend
| Month | Combined shipments / YoY | What the sequence says |
|---|---|---|
| January | 440,819 / -29.2% | The contraction carried into 2026. |
| February | 638,841 / +0.4% | The first positive year-over-year month after the decline streak. |
| March | 856,674 / +4.6% | Recovery broadened. |
| April | 837,098 / +5.1% | Growth continued despite still-negative YTD totals at that point. |
| May | 919,685 / +6.7% | A fifth consecutive improvement versus the prior year. |
| June | 1,023,571 / +21.7% | The recovery accelerated sharply. |
| July | 916,830 / +20.1% | A second straight month above 20% year-over-year growth. |
The base effect is doing real work in that 20% number
A contractor looking at a dashboard knows this problem immediately: percentage growth depends on what is underneath it.
July 2025 was unusually weak. AHRI reported 763,443 combined units that month, compared with 1,043,420 in July 2024. That was a drop of roughly 26.8%.
So July 2026's 20.1% gain is encouraging, but it does not recover all of the prior year's decline. At 916,830 units, July 2026 is still about 126,590 units—or 12.1%—below July 2024.
The year-to-date totals are less volatile and therefore more useful for judging the broader channel. Through July 2026, manufacturers shipped 5,633,518 combined central AC and heat-pump units. That is 292,934 more than the same period in 2025, but 126,433 fewer than the same period in 2024.
The conclusion is more useful when stated precisely: 2026 has regained meaningful ground from 2025. It has not yet surpassed the 2024 shipment pace.
July and year-to-date volume: 2024 vs. 2025 vs. 2026
| Measure | 2024 | 2025 | 2026 |
|---|---|---|---|
| July combined AC + heat pumps | 1,043,420 | 763,443 | 916,830 |
| Jan.–July combined AC + heat pumps | 5,759,951 | 5,340,584 | 5,633,518 |
| Jan.–July central AC | 3,332,577 | 2,911,784 | 3,063,290 |
| Jan.–July air-source heat pumps | 2,427,374 | 2,428,800 | 2,570,228 |
Heat pumps are gaining share even before the total market fully recovers
The mix shift inside the combined category is just as important as the total.
Through July 2026, AHRI reports 2,570,228 air-source heat pumps and 3,063,290 central air conditioners. Heat pumps therefore represent about 45.6% of combined year-to-date shipments. Over the same period in 2024, heat pumps represented about 42.1%. That is an increase of roughly 3.5 percentage points in two years.
In absolute terms, the comparison is striking. Year-to-date heat-pump shipments are about 142,854 units above 2024, while central-air shipments are about 269,287 units below 2024. The combined market remains smaller than it was two years ago, but heat pumps occupy more of it.
For a contractor, that matters beyond policy debates about electrification. A changing equipment mix affects training, commissioning, diagnostics, controls knowledge, cold-climate expectations, parts stocking and how salespeople explain operating tradeoffs. A market can be flat or recovering slowly while the technical work inside it changes materially.
Gas furnaces are not sending the same signal
Warm-air furnace shipments complicate any broad claim that the entire residential HVAC equipment market is accelerating at the same pace.
AHRI says gas warm-air furnace shipments increased 2.1% in July to 265,810 units. Yet year-to-date gas-furnace shipments remain down 5.1%, at 1,818,744 units versus 1,915,641 in the same period of 2025.
Oil furnaces posted a 36.6% July increase and a 13.9% year-to-date gain, but the category is tiny by comparison: 2,681 units in July and 17,641 year to date.
The divergence is a reminder that “HVAC demand” is not one number. Cooling equipment, heat pumps and furnaces can move in different directions because of replacement cycles, regional weather, channel inventory, product transitions, housing activity and customer economics. Contractors should resist turning a national combined-shipment headline into a blanket assumption about every department of the business.
Shipments are upstream. Contractors live downstream.
AHRI's definition is important: a shipment occurs when a unit transfers ownership. That makes the series a valuable measure of equipment moving through the U.S. channel, but it does not tell you when—or whether—a specific unit was installed in a homeowner's house.
Manufacturer shipments can move because distributors are rebuilding inventory, clearing product, preparing for seasonal demand or responding to product-transition timing. Weather can pull orders forward. A weak prior-year comparison can make growth rates look stronger. Local replacement demand can diverge substantially from the national average.
That does not make the data less useful. It tells operators how to use it. Treat shipment data as an upstream signal that should be reconciled against downstream operating data rather than substituted for it.
If your local business is seeing the same recovery, it should eventually appear in several places at once: more eligible replacement calls, more system-replacement estimates, higher booked replacement volume, improving close rates without destructive discounting, stable or improving gross profit, and distributor availability that supports the work.
If national shipments are rising but those indicators are not, the gap is itself useful information. It may point to local market weakness, share loss, lead-generation problems, sales execution, financing friction or a channel effect that has not reached the field.
The contractor dashboard that should confirm—or challenge—the national recovery
| Metric | What improvement would look like | What a mismatch may reveal |
|---|---|---|
| Replacement opportunities | More qualified system-replacement calls and estimates | Local demand may still be soft or the lead mix may be wrong |
| Close rate | Stable or improving conversion at disciplined pricing | Sales process, financing or affordability friction |
| Average replacement ticket | Healthy mix without relying on discounting to create volume | Price resistance or product-mix compression |
| Gross profit dollars | Volume growth that also creates contribution | Revenue growth may be coming at the expense of margin |
| Financing usage and approval | Customers can still convert high-ticket replacements | Credit availability may be constraining demand |
| Distributor inventory | Availability supports sold work without excessive channel loading | Shipment growth may be sitting upstream rather than turning into installs |
| Cancellation / reschedule rate | Booked work holds through installation | The funnel may look stronger before the final conversion point |
What owners should do with the July data
- Pull a 13-month replacement dashboard. Compare eligible replacement opportunities, estimates, close rate, average ticket, installed gross profit and financing usage—not just top-line revenue.
- Separate repair from replacement. A strong service-call count can hide weak equipment conversion, while a replacement rebound can be diluted inside an all-service average.
- Ask distributors what is actually moving. Compare sell-through, backorders and on-hand inventory with the national shipment trend so you can distinguish field demand from channel restocking.
- Review heat-pump readiness. The category is taking a larger share of combined shipments, so training, commissioning, controls and sales education should follow the mix shift even in markets where gas remains important.
- Protect margin as volume returns. A recovering market is not a reason to stop monitoring equipment cost, discounting and quote validity. Dispatch recently documented September HVAC supplier price increases that can make an old estimate a new margin problem.
- Do not budget the rest of 2026 from one month. Use the six-month direction as evidence of recovery, then update the operating plan as August and fall shipment data arrive.
Related Dispatch analysis: supplier increases can erase the benefit of stronger volume
September HVAC price increases are landing across common equipment and materials. Dispatch's margin analysis shows why a recovering sales environment still requires current price books and disciplined quote windows.
Also watch the install side: the HVAC GFCI exception expired September 1
Equipment volume is only one operating variable. Contractors are also navigating a state-by-state code patchwork after the NEC 210.8(F) HVAC exception expired.
The useful word is recovery
July gives the HVAC market a genuinely better data point than it had at the start of the year.
A 20.1% increase is substantial. Six consecutive positive year-over-year months make the directional case stronger. Central air is growing, heat pumps are growing and year-to-date combined shipments are back above 2025.
But the longer comparison keeps the story grounded. July remains below July 2024. The first seven months of 2026 remain below the same period in 2024. Gas-furnace shipments remain down year to date. And shipments themselves do not equal installations, booked revenue or profitable jobs.
So the operator's question is not whether a national trade-association release has declared the market healthy. It has not.
The question is whether the recovery visible upstream is now reaching your own funnel—and whether your company is positioned to convert it when it does.
Questions contractors may have about the AHRI shipment data
Did HVAC shipments rise 20% in July 2026?
Combined U.S. shipments of central air conditioners and air-source heat pumps rose 20.1% year over year to 916,830 units in July 2026, according to AHRI. Central AC rose 22.3% and heat pumps rose 17.6%.
Does that mean HVAC replacement demand rose 20%?
No. AHRI reports manufacturer shipment transfers, not contractor installations or homeowner purchases. The data is an important upstream market signal, but contractors should compare it with their own replacement opportunities, sales and completed jobs.
Are 2026 HVAC shipments now above 2024?
Not through July. Combined year-to-date shipments are 5.63 million units in 2026 versus 5.76 million over the same period in 2024, about 2.2% lower. July 2026 volume is also about 12.1% below July 2024.
Are heat pumps still gaining share?
Yes within AHRI's combined central AC and air-source heat-pump shipment category. Heat pumps are about 45.6% of year-to-date 2026 combined shipments, compared with about 42.1% over the same period in 2024.
Methodology
TradeVulcan Dispatch reviewed AHRI's July 2026 statistical release and prior monthly AHRI releases, then cross-checked the latest figures against Contracting Business and HomePros coverage published September 11, 2026. Percent comparisons to 2024 are Dispatch calculations from AHRI's published July and year-to-date totals: 916,830 versus 1,043,420 for July (-12.1%) and 5,633,518 versus 5,759,951 year to date (-2.2%). Heat-pump shipment share is calculated as 2,570,228 divided by 5,633,518 (45.6%) for 2026 and 2,427,374 divided by 5,759,951 (42.1%) for 2024. AHRI defines a shipment as a transfer of ownership; the series does not represent installations, booked jobs or contractor revenue and is not seasonally adjusted in this analysis. AHRI states that it does not forecast or discuss market trends; all interpretation is Dispatch analysis.
Sources
- AHRI Releases July 2026 U.S. Heating and Cooling Equipment Shipment Data — Air-Conditioning, Heating, and Refrigeration Institute
- July 2026 Statistical Release — Air-Conditioning, Heating, and Refrigeration Institute
- HVAC shipments extend recovery streak to six months in July — HomePros
- AHRI: July HVAC Shipments Rebound With Strong AC Growth — Contracting Business
- AHRI Releases January 2026 U.S. Heating and Cooling Equipment Shipment Data — Air-Conditioning, Heating, and Refrigeration Institute
- AHRI Releases February 2026 U.S. Heating and Cooling Equipment Shipment Data — Air-Conditioning, Heating, and Refrigeration Institute
- AHRI Releases April 2026 U.S. Heating and Cooling Equipment Shipment Data — Air-Conditioning, Heating, and Refrigeration Institute
- AHRI Releases December 2025 U.S. Heating and Cooling Equipment Shipment Data — Air-Conditioning, Heating, and Refrigeration Institute